Business
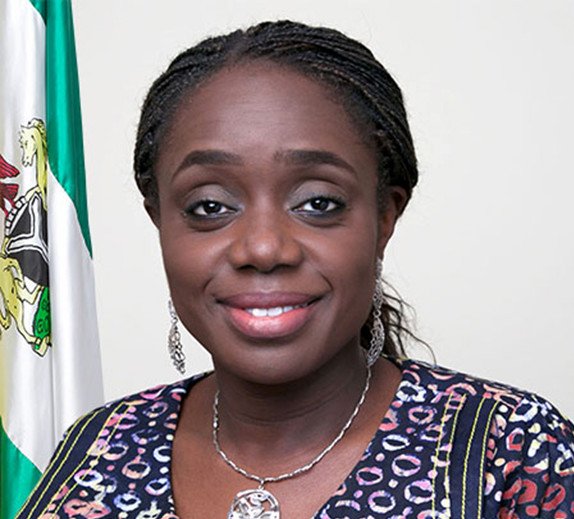
Nigeria is ready to access IMF loan – Adeosun

After several delay, Nigeria will this Wednesday approach the International Monetary Fund (IMF) to finalise its “policy support document” needed to complete its application for funds to help plug the $11bn budget deficit.
The Minister of Finance, Kemi Adeosun, who stated this at the weekend in an
Interview with Financial Times said what was delaying the loan was the lack of flexibility in exchange rate which the country now has.
Adeosun said the delayed passage of the 2016 budget had stalled the start of those projects to the fourth quarter. By then, she said, Nigeria would have secured funding from abroad for the record N6.1tn budget, quashing concerns that funding would not be available in time for the projects to begin this year.
She also said the Federal Government was hopeful of an economic revival, even as the country slides into recession.
ALSO SEE: Federal, state, local governments share N559bn
Adeosun said the government did not dispute the International Monetary Fund’s forecast last week that the economy would contract by 1.8 per cent.
“We’re simply saying that we have a very credible plan for dealing with the challenges we are facing, which we’ve been very honest about,” she said.
The central bank’s decision last month to remove a 16-month-old peg on the value of the naira is the signal that international lenders, including the World Bank, have been waiting for, she added.
Low global oil prices have helped push Africa’s biggest economy into its worst economic crisis in decades. But many economists believe policies adopted by the central bank during the first year of Buhari’s presidency exacerbated the problem.
Although the minister thinks “there is still a long way to go,” the government is convinced that “diversifying and repositioning” the oil-dependent economy will bear fruit.
Part of that diversification includes the agricultural sector, where a boost in output is expected this year. Aggressive management of food price inflation, which includes low cost loans to farmers and improved distribution of fertiliser, will help bridge the shortfall in oil revenues, she said.
Investors have also viewed the greater flexibility in the foreign exchange market as a step in the right direction. But restrictions on hard currency allocation to import raw materials are still hurting manufacturers and leaving investors hesitant to bring their money back in.





-
 Featured5 days ago
Inside INEC’s race to prepare for Nigeria’s 2027 elections
-
 Featured5 days ago
2027: APC unveils nationwide campaign timetable, Tinubu to rally in 12 states
-
 Latest7 days ago
UCTH faces morgue crisis as 50 unclaimed corpses await mass burial
-
 Business7 days ago
BREAKING: Nigeria’s Inflation Rate Drops to 14.63% in September
-
 Business6 days ago
President Tinubu and the Low Transport Fares Fiasco
-
 Business5 days ago
Court dismisses ₦170m Trade Fair contract claim, says Zenith Bank was not a party
-
 Business2 days ago
Naira faces exchange rate gap as Dollar hits N1,380 on parallel market
-
 Latest5 days ago
Breaking: NNPCL raises petrol price to ₦1,405 per litre amid discount controversy