Business
PalmPay upgrades security centre as digital fraud risks evolve in Nigeria

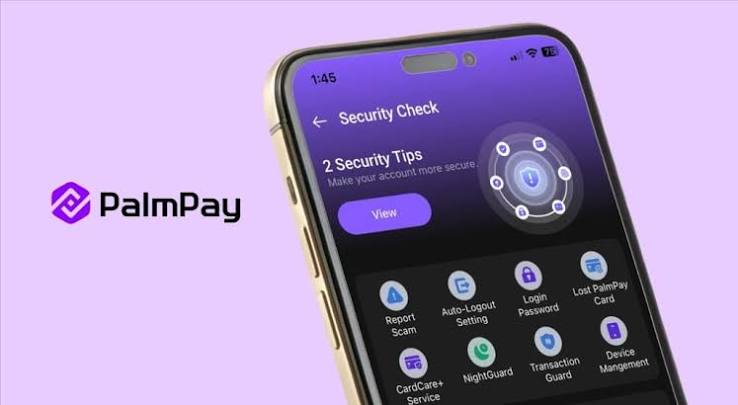
PalmPay has upgraded its Security Centre with additional account and transaction protection tools as fraud risks continue to evolve across Nigeria’s increasingly digital financial system.
The fintech company said the upgrade, introduced as part of its “PalmPay Dey For You” campaign, brings several security controls into a single platform to help customers respond to suspicious activity and reduce exposure to unauthorised transactions.
The new features include Real-Time Security Check, Large Transaction Shield, Night Guard, USSD account and card lock, as well as transaction alerts for suspected fraud recipients, duplicate transfers and logins from new devices.
The Night Guard feature allows customers to set a protection period between 11pm and 7am. Transfers attempted during the selected period require additional verification before they can be completed.
PalmPay has said the feature is intended to provide an additional layer of protection, particularly where a customer’s phone has been lost or compromised and suspicious transactions are attempted at night.
The Large Transaction Shield similarly introduces an additional verification step for large-value transactions, while USSD and card-lock functions allow customers to restrict access to their accounts when their phones or cards are lost or stolen.
The Security Centre also provides alerts relating to potentially fraudulent recipients, duplicate transfers and logins from unfamiliar devices.
According to Tosin Obadimu, Head of the Fraud Management Department at the Nigeria Inter-Bank Settlement System (NIBSS), bringing the controls together could strengthen verification around higher-risk transactions and make it easier for customers to report suspected fraud.
Obadimu said the measures could help address risks associated with social engineering and account takeover, while integrated dispute and fraud-reporting mechanisms could improve the speed of incident reporting and potential recovery of funds.
Nigeria’s rapid adoption of mobile banking, fintech applications, electronic transfers and other digital payment channels has also created new opportunities for fraudsters.
Rather than relying solely on traditional methods, criminals increasingly use techniques designed to manipulate users into voluntarily disclosing information or authorising transactions.
These include phishing messages, fake websites, impersonation, social engineering, SIM-related attacks and attempts to gain control of customers’ devices or accounts.
The Central Bank of Nigeria warns that phishing and social-engineering scams can involve criminals impersonating legitimate organisations or trusted individuals to obtain sensitive financial information. The regulator advises customers to avoid suspicious links, verify requests for personal information and contact their financial institutions directly when in doubt.
Available industry data suggests that electronic-payment fraud losses declined significantly in 2025, although the level of fraud remained substantial.
Data presented by NIBSS at the 2026 Nigeria Electronic Fraud Forum showed that Nigerian banks and financial institutions recorded approximately ₦25.85 billion in losses to electronic-payment fraud in 2025, representing a 51 per cent decline from the ₦52.26 billion recorded in 2024.
The number of reported cases also fell to about 67,515 in 2025, according to the data.
However, separate figures contained in the CBN’s Nigeria Payments System Vision 2028 indicate the broader scale of the problem. Between 2020 and 2025, attempted fraud across Nigeria’s banking and payments ecosystem amounted to approximately ₦187.79 billion, with actual losses estimated at ₦134.48 billion.
The figures covered multiple channels, including internet and mobile banking, ATMs, point-of-sale terminals, e-commerce and other electronic payment platforms.
The difference between the figures reflects different periods, definitions and data sets, but both point to the continuing challenge of protecting increasingly digital financial transactions.
Technology alone cannot eliminate financial fraud.
Security tools can add layers of protection, but fraudsters can still attempt to manipulate customers into revealing passwords, PINs, one-time passwords or other sensitive information.
PalmPay has therefore included customer education in its latest campaign, particularly around impersonation and other common forms of digital fraud.
The company’s Chief Operating Officer, Samuel Oluyemi, said financial-service providers need to continually adapt their fraud-management strategies as customer behaviour and payment channels change.
The wider financial industry faces a similar challenge: balancing convenient and fast digital transactions with adequate safeguards against increasingly sophisticated attacks.
PalmPay’s security upgrade comes at a time when digital payments have become deeply embedded in everyday economic activity in Nigeria.
Customers increasingly use mobile applications and electronic transfers to pay bills, purchase goods, receive salaries and conduct business. As more financial activity moves online, protecting digital accounts becomes an issue involving not only individual fintech companies but banks, payment processors, telecommunications operators, regulators and law-enforcement agencies.
For consumers, basic precautions remain important. Customers should avoid sharing PINs, passwords or one-time authentication codes, should verify unexpected payment requests independently and should immediately contact their financial institution if a phone, card or account is compromised.
The CBN also advises customers to report suspected fraud promptly and secure compromised accounts.
PalmPay’s upgraded Security Centre is therefore part of a broader response to an evolving problem. Its effectiveness will depend not only on the availability of new technical controls but also on how widely customers use them, how quickly suspicious transactions are detected and reported, and how effectively financial institutions work together to prevent and recover fraudulent funds.
-
 Latest5 days ago
Pastor Chris Oyakhilome announces mother’s passing at 88 [VIDEO]
-
 Latest6 days ago
Arsenal eye €70-80m move for Real Madrid star
-
 Crime6 days ago
Police arrest suspect, launch manhunt for 2 others over Delta Education Director’s death
-
 Crime5 days ago
Deaths in NSCDC Custody: Can Nigeria guarantee the safety of detainees?
-
 Latest5 days ago
How adulterated palm oil, coloured pepper are putting consumers at risk
-
 Latest6 days ago
Obi left $155m in Anambra, Otti insists amid debt controversy
-
 Football3 days ago
How David Beckham made $51.1m from 2026 World Cup, surpassing winners’ prize
-
 Crime6 days ago
184.5kg Cocaine Bust: NDLEA docks KC Luxury, two accomplices, remands them in custody