Business
Bitcoin: Taking the world by storm

By Odunewu Segun
That virtual currencies are already playing a key role in the unsteady financial systems of some developing markets, Nigeria inclusive is not in doubt, but the question on many lips is if it could be sustained on the long run.
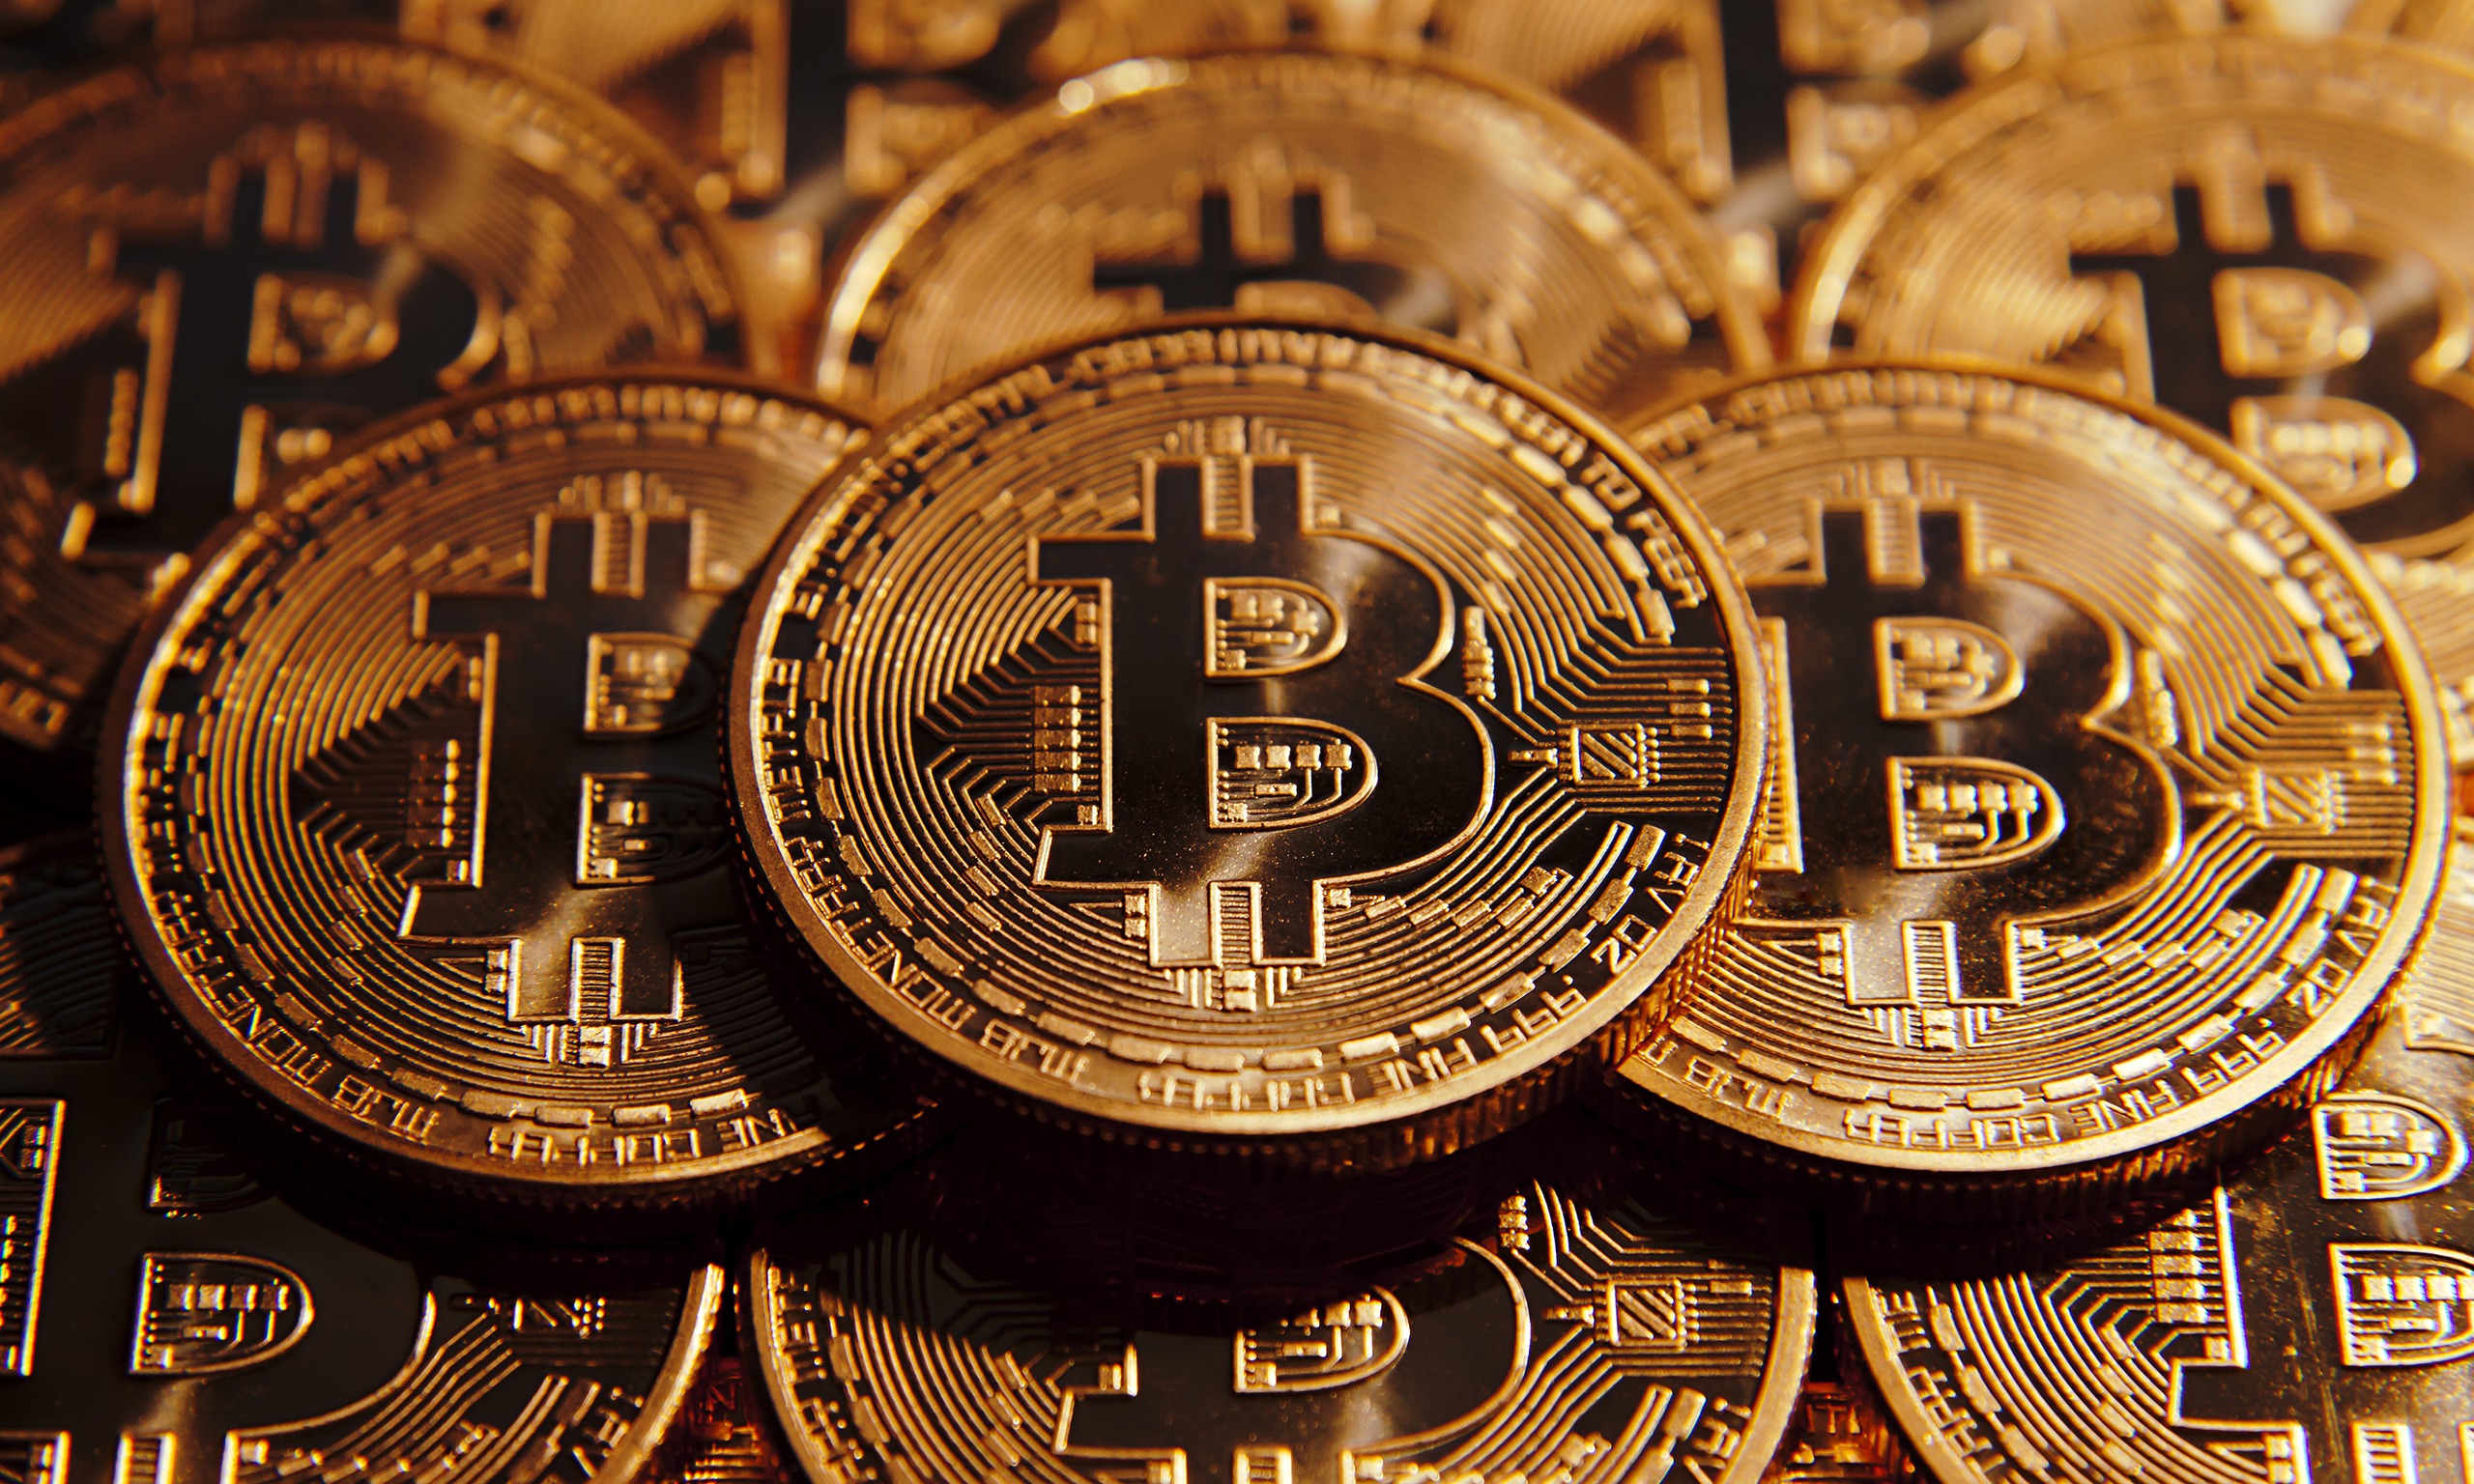
According to recent estimates, there are over 6,000 complementary currencies in the world, over 50 times the number of conventional money systems. But far the most popular is Bitcoin.
Bitcoin, much like the internet in 1994, is not easily explained or understood. Its advocates compare the technical innovation with that of the World Wide Web. But while the internet changed the way people communicate, Bitcoin changes the way people view and use money.
Bitcoins were launched in 2009 in the wake of the global financial crisis by an anonymous programmer who wanted to create a currency independent of any central bank or financial institution.
A form of “e-money”, it is made of strings of dazzlingly complex code created by raw computing power — a process called “mining” that can in theory be carried out by anyone with a computer.
Once mined, Bitcoins are stored on a user’s hard drive in a virtual wallet, and can be sent directly to another person. Such peer-to-peer sharing bypasses the banks so is largely anonymous. But this brings its own risks — in June 2011, hackers targeted virtual wallets and wiped some people’s accounts clean.
But for Naud, an asset manager, Bitcoin is reaching unsustainable levels. On paper at least, the value of Bitcoins in circulation now tops $40 billion, and a continued increase in price will require a lot of new investors.
ALSO SEE: Bitcoin drops to its lowest level in June
“The bubble will burst when there will be less people willing to enter (the Bitcoin market) than people willing to leave it,” he said. “It’s hard to pinpoint, but it probably won’t last another month at this price.”
Developed economies are gradually welcoming the trend despite initial resistance. Japan, China, the US among other countries are increasingly accepting cryptocurrencies as both a method of payment and store of value.
Developing economies, too, are not left out in this rush to embrace virtual currencies. In South Africa, Nigeria and some dozens of African countries, cryptocurrencies are becoming particularly popular.
In Nigeria for instance, local traders and activists believe this new money presents an opportunity to democratize the economy following the abysmal performances of the Naira against international currencies such as the Dollar and Pound Sterling.
But experts said Bitcoins are especially vulnerable to rapid deflation. Governments trying to regulate them, for example, could spook investors and cause them to lose confidence.





-
 Featured6 days ago
Inside INEC’s race to prepare for Nigeria’s 2027 elections
-
 Latest1 week ago
Global excitement builds as Healing Streams Live Services returns October 23
-
 Featured6 days ago
2027: APC unveils nationwide campaign timetable, Tinubu to rally in 12 states
-
 Business1 week ago
President Tinubu and the Low Transport Fares Fiasco
-
 Business3 days ago
Naira faces exchange rate gap as Dollar hits N1,380 on parallel market
-
 Business6 days ago
Court dismisses ₦170m Trade Fair contract claim, says Zenith Bank was not a party
-
 Latest6 days ago
Breaking: NNPCL raises petrol price to ₦1,405 per litre amid discount controversy
-
 Business1 week ago
Rite Foods targets beverage market growth with LIDA Malt