Business
Fitch downgraded Coronation Merchant Bank IDR over weakened capital position

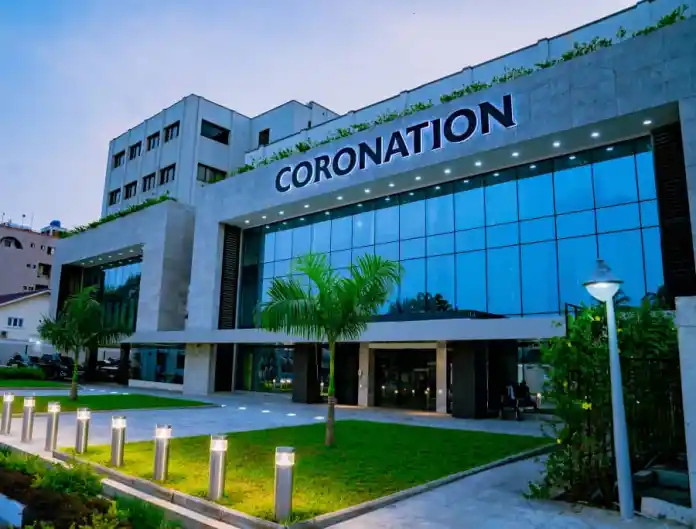
The Long-Term Issuer Default Rating (IDR) of Coronation Merchant Bank (CMB) has been downgraded by Fitch Ratings to ‘CC’ from ‘B-‘, with its Viability Rating (VR) also lowered to ‘cc’ from ‘b-‘.
In a note released by the rating agency, it also demoted the bank’s National Long-Term Rating to ‘B+(nga)’ from ‘BBB-(nga)’, raising some red flags that prompted its latest decision.
According to Fitch, CMB was moved down in the pecking order due to a “significantly weakened capital position”, which if not quickly addressed, “could lead to a material capital shortfall.”
Already, the financial institution is taking a step to bolster its capital base through a rights issue, as pointed out in the statement released by Fitch on November 20, 2023.
In the disclosure, which was seen by Business Post, it was emphasized that the capital position of CBM, which it said was threatened, “reflects a weakening in the bank’s foreign-currency (FC) liquidity, considering a diminished ability to refinance upcoming FC debt maturities in view of the estimated significant weakening in capitalisation.”
READ ALSO: Cash transfers can save Nigerians from falling deeper into poverty – World Bank
Fitch further stressed that the Long-Term IDR of the company reflects its “view that a default on the bank’s senior obligations is probable in view of heightened FC liquidity risk,” adding that the bank’s “creditworthiness has weakened relative to that of Nigerian peers.”
Explaining why the capitalization of CMB is weak, the rating firm said the sharp depreciation of the Naira since June 2023 and weak profitability resulting from the Central Bank of Nigeria’s (CBN) highly punitive cash reserve ratio (CRR) requirement affected the company.
It noted that this would likely impact negatively on the lender’s “ability to refinance large upcoming FC debt maturities.”
Fitch pointed out in the statement that last year, Coronation Merchant Bank reported a large net loss in the form of a negative return on average equity (ROAE) of 25 percent as a result of negative net interest margins.
It stated that the negative net interest margins resulted from a high cost of funding combined with high exposure to low-yielding government securities, including CBN-issued special bills and unremunerated cash reserves at the CBN.
The firm noted that this action of the apex bank on the CRR, following its reduction 10 per cent from 32.5 per cent for merchant banks in July 2023, has continued to affect the bank’s earnings.
However, the rating company disclosed that the ratings of the merchant bank could be raised if its capital position improves and its FC liquidity risks ease.






-
 Latest7 days ago
US Immigration fees rise from October 16 as USCIS announces new charges
-
 Latest2 days ago
Israel marks 3 years since October 7 Hamas attack amid Gaza strikes, election debate
-
 Business6 days ago
Nigeria’s $55bn reserves raise fresh questions over naira value
-
 Health6 days ago
Florida sues Pfizer over deceptive COVID-19 vaccine marketing
-
 Business1 week ago
Tuoyo Erikowa wins digital marketing personality of the Year at 2026 EDGE awards
-
 Crime6 days ago
From camp to captivity: How kidnappers now target NYSC Corps members on highways
-
 Featured7 days ago
2027: Can Nigeria’s opposition still unite behind a single presidential candidate?
-
 Crime6 days ago
Fulani Militia leader linked to Christian killings arrested in Plateau